Research Minute: 3 takeaways from The 47G Report
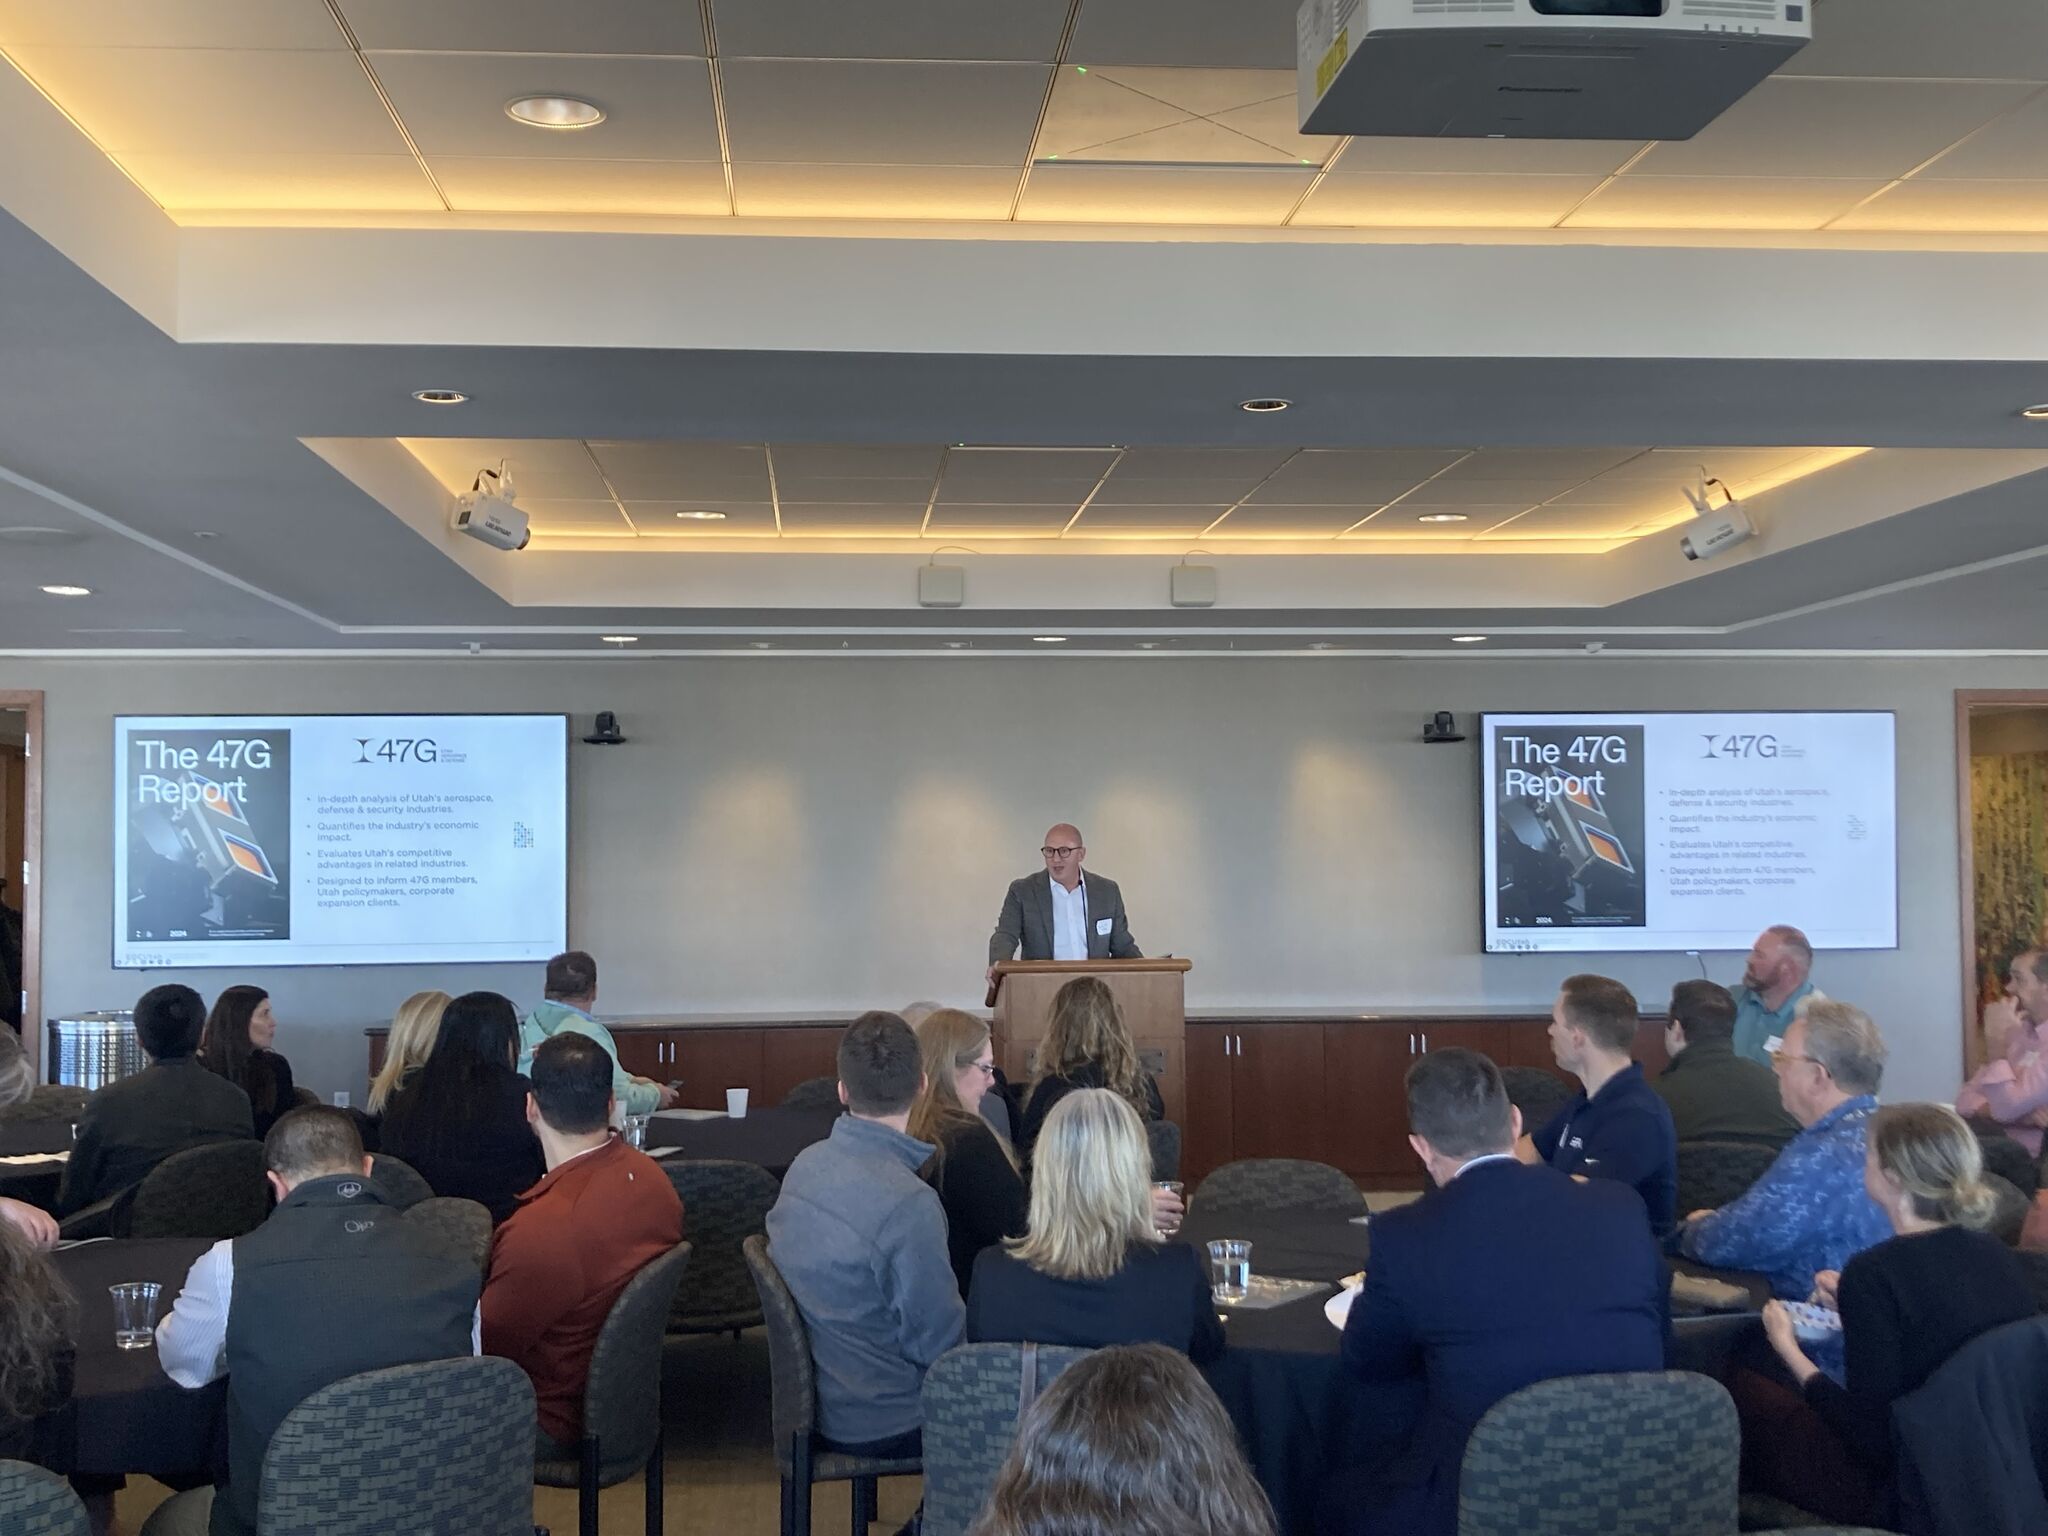
Each year, the EDCUtah research team publishes data on several key industry clusters in Utah. These industry profiles include information like cost comparisons, labor density, and key employers in the industry. More recently, 47G commissioned EDCUtah to conduct an in-depth analysis of Utah’s broader aerospace, defense, and security industries.
The 47G Report set out to quantify the economic impact of aerospace and defense activity in Utah, as well as adjacent industries such as advanced materials manufacturing and cybersecurity technology. The report also evaluates the Beehive State’s competitive advantages in related industries. It offers valuable insights to better inform 47G members, Utah policymakers, and corporate expansion clients looking to bring their aerospace, defense, and security operations to Utah.
Here are a few takeaways from the report:
The EDCUtah Research team analyzed data collected by multiple federal, state, and private organizations to examine the broader aerospace and defense industry in Utah. The broader industry includes the traditional guided missile and aerospace vehicle parts manufacturing as well as national security, space research, and their critical supply chains. Because of tech’s growing influence on aerospace and defense, sectors like artificial intelligence, cyber security, machine learning, and other activities critical to domestic and internet security are included in the analysis.
This broader definition of aerospace and defense yields impressive statistics that demonstrate its importance to Utah’s economy. In 2023, the industry:
Utah has a rich history and legacy of aerospace and defense in the state. The state is home to multiple military installations, research facilities, and private companies that contribute to the success of the industry.
Since its establishment in 1939, Hill Air Force Base has been a key installation specializing in aircraft maintenance, repair, and overhaul. It is also home to the Ogden Air Logistics Complex, which maintains and modernizs Air Force aircraft and weapon systems. Other notable military installations in Utah include Camp Williams, the Roland R. Wright National Guard Base, and the Tooele Army Depot, among others.
According to the Milken Institute, the University of Utah ranks no. 1 in the institute’s Technology Transfer and Commercialization Index and Brigham Young University ranks no. 4. This index measures a university’s efficacy of utilizing its research and development capabilities to develop new technologies that can be applied outside of the university. These two universities ranked higher than notable universities such as Stanford University and the Massachussetts Institute of Technology (MIT). Utah is also home to research facilities such as the Space Dynamics Lab at Utah State University, Falcon Hill Aerospace and Research Park, and the Dugway Proving Grounds. These facilities contribute to the advancement of space and weapons research that are critical to both the nation’s defense and Utah’s strong economy.
Finally, Utah is home to companies such as Boeing, Duncan Aviation, L3Harris, Lockheed Martin, and Northrop Grumman—many of which had at least one corporate expansion project with EDCUtah. These companies contribute to maintaining a highly skilled labor force in Utah and, in turn, benefit from the state’s significant educational assets.
EDCUtah estimated the total economic impact of the broader aerospace, defense, and security industry. This analysis is comprised of three four parts: direct, indirect, induced, and total impact.
The direct impact is the immediate, quantifiable metric in the industry. For example, the industry employs over 236,000 individuals directly in the industry. Additionally, businesses in the industry require inputs for the goods and services that they provide. In engaging with the broader economy to acquire these inputs, they create jobs and income that is captured as indirect impact. Finally, the wages of the direct and indirect employees are spent on the broader economy, creating induced impact. The total impact simply combines the direct, indirect and induced impacts to see how the industry affects the region’s economy.

The results of this analysis show that the industry has a doubling effect on employment with a multiple of 2.02. This means that every direct job in the industry results in another job due to its indirect or induced effects. While the multiples aren’t quite as large for the output and compensation numbers, they are still notable with total impacts of 1.77 and 1.86.

For a deeper dive into the aerospace, defense, and security industry in Utah, contact EDCUtah at connect@edcutah.org or 47G at contact@47g.org. This report is not yet accessible online, but a physical copy may be requested.
_____
Each month, EDCUtah’s Research Minute highlights interesting economic development data and timely research insights. Want more data? Explore the benefits of investing with EDCUtah.
For additional information or to schedule an interview, please contact us.
Each month, EDCUtah’s Research Minute highlights interesting economic development data and timely research insights. This month, we review rent affordability in the U.S. and how Utah compares.
Housing affordability in Utah has been a hot topic for both residents and businesses across the state. According to three different sources — Zillow, Redfin, and CoStar — residential renting became more affordable for Utahns in 2024, while becoming generally less affordable in the United States. While the cost of purchasing a home in Utah continues to rise, there is room for optimism now that rent prices have stabilized and even decreased, making the market more affordable for Utah’s renters.
Zillow and Redfin, two online real estate market and brokerage services, frequently publish reports on trends that their internal data shows in the housing market. Similarly, CoStar tracks real estate data and EDCUtah uses that data to see how these trends impact our state. Each publishes data on rent prices but they reported different changes in rent based on their data on both the national and local scale. Redfin and Zillow only use major metro areas in their analysis, so they were only able to report on the Salt Lake metro. CoStar has data on Utah’s other metro areas that show similar trends to the Salt Lake metro. This report will focus on the Salt Lake metro because of the two reports recently released by Redfin and Zillow.
Zillow, Costar, and Redfin reported rent increases of 3.5%, 1.1%, and 0.1% respectively across the nation in 2024. This variance in values is expected since each source is pulling from a different sample of real estate throughout the country. Although there is disagreement in the exact rate of rent growth across the country, there is agreement that prices are still rising and may be stabilizing from the extreme growth in prices that peaked in 2022.
Meanwhile, Zillow was the only source that saw an increase in the price of rent in the Salt Lake City metro, with only a 0.3% increase in prices, while Redfin and CoStar reported that the metro decreased rent prices by 6.5% and 1.1% respectively. Zillow ranked the Salt Lake City metro as the third most affordable metro for renters in the United States, and Redfin ranked Salt Lake City as the fourth most affordable metro in the nation.
Wages have generally increased nationwide, and Redfin’s report looked into this wage growth to better understand affordability. Using Census Bureau data, they estimated that the median income for American renters increased by 5.3% in 2024. They found this increase in median wages was greater than the increase in rent prices, thus making rent more affordable nationwide. Still, the median renter in the United States is allocating 34.9% of their income to housing expenses. For the Salt Lake City metro, Redfin determined that the median renter is allocating roughly 27.5% of their income for housing, while Zillow’s report suggests that Salt Lake City renters are able to allocate an even smaller proportion of their income to housing, at 19.9%.
CoStar suggests that the decrease in rental prices is likely due to the completion of many multifamily housing units in 2024. While this is true, 2024 also saw much fewer multi-family housing units begin construction than had begun in previous years. For Salt Lake City metro to maintain housing affordability while growing in population and opportunity, building additional units will remain important to meet growing demand.
_____
Want more data like this? Explore the benefits of investing with EDCUtah.
For additional information or to schedule an interview, please contact us.
Each month, EDCUtah’s Research Minute highlights compelling economic development data and timely research insights. This month, we highlight the recently published Utah Innovation Ecosystem Report.
Utah’s broad innovation ecosystem ranks high among U.S. states across various measures, according to a new study produced jointly by EDCUtah and the Kem C. Gardner Policy Institute. The study, titled Utah Innovation Ecosystems, highlights the state’s top-ranking performance in innovation capacity and outcomes, driven by a combination of strategic strengths and industry-aligned ecosystems.
The report was commissioned by Utah Governor’s Office of Economic Opportunity and the Utah Policy Innovation Lab to examine the characteristics that contribute to the Utah’s success in innovation and identify gaps or opportunities for improvement. The results of the study offer insights that can help inform Utah’s entrepreneurs, investors, educators, and policymakers.
Here are a few takeaways from the report.
The report found that Utah ranks first in the nation on the Innovation Intelligence Index developed by the Indiana Business Research Center. This index evaluates critical attributes of innovation, including human capital and knowledge creation, business dynamics, business profile, employment and productivity, and economic well-being. Utah’s consistent performance across all these categories, ranking sixth or better in each, cements its status as a hub for innovation and economic growth.

An innovation ecosystem is the dynamic set of actors, activities, artifacts, institutions, and relationships that influence and are essential for the innovative performance of an individual or group. This includes not only direct relationships, but also complementary and substitute relationships, forming a complex and evolving environment for innovation.
Utah’s success is driven by five distinct, industry-aligned ecosystems:
These ecosystems represent varying levels of maturity but collectively contribute to the state’s competitive innovation landscape.

Utah’s potential innovation strengths and opportunities for growth were identified by conducting in-depth interviews with industry experts throughout the state as well as other qualitative analyses. Utah’s core strengths include the role of higher education in cultivating a skilled workforce, a strong culture of entrepreneurship, and the existence of social infrastructure that encourages collaboration among key stakeholders.
The report also outlines areas where Utah could further enhance its innovation ecosystems. Opportunities for growth include the further development of physical infrastructure, particularly research facilities, incubation spaces, and innovation hubs. Additionally, continuing to attract venture capital and other funding sources remains critical, especially in sectors like aeronautics, energy production, and health care.
By addressing these potential gaps, Utah has the opportunity to not only sustain but also accelerate its trajectory as a leader in innovation. The state’s strategic focus on infrastructure, funding, and collaboration will be crucial in ensuring long-term economic growth and continued success in fostering innovation and maintaining Utah’s status as one of the best states in the nation for innovation and economic growth.
_____
For more data like this, email us at connect@edcutah.org or explore the benefits of investing with EDCUtah.
For additional information or to schedule an interview, please contact us.
Each month, EDCUtah’s Research Minute highlights interesting economic development data and timely research insights. This month, we explore the Archbridge Institute’s Social Mobility score and how Utah earned the no. 1 rank in the country.
Utah ranks first in the nation for social mobility in the 2023 Social Mobility in the 50 States report published by the Archbridge Institute. For residents, this translates to a better chance of moving up the social and economic ladder in Utah than in any other state. For businesses, this makes Utah an attractive location because it gives their workforce the best opportunity to live the American dream.
Social mobility has typically referred to the ability of individuals to surpass the earnings of their parents at the same age. In their research to create a social mobility index, the Archbridge Institute included not only this intergenerational income element, but also metrics that more broadly measure one’s ability to improve their life and well-being. Archbridge Institute applied four pillars to the index:
Archbridge Institute analyzed each pillar for all 50 states and ranked them by their scores. Utah ranked no. 1 for overall social mobility, no. 4 for Entrepreneurship and Growth, no. 5 in Education and Skills Development, no. 8 in Social Capital, and no. 17 for Institutions and Rule of Law.
Each of the four pillars contained additional subcategories of measurement. While the report does not give detailed descriptions of the specific data used to generate the rankings, they can still provide insights into general areas of strength and improvement. The subcategories where Utah showed its greatest strengths were:
Utah’s lower rankings appeared in the following subcategories:
While there is room for improvement in Utah’s social mobility, it should be noted that even Utah’s lower rankings just barely fall in the bottom half of all 50 states. Utah is not far from sitting in the top half for all subcategories.
But how does the Archbridge Institute index compare to more traditional measures of social mobility? The index aligns closely with income mobility, poverty rates, and income inequality data for Utah. In a 2014 study, for example, Salt Lake City had the highest score for intergenerational mobility out of the 50 largest community zones in the country. Additionally, Utah has the nation’s second lowest poverty rate (9%) and the lowest level of income inequality as measured by the Gini Index. (Both of these Utah data comparisons use the U.S. Census Bureau’s 2023 American Community Survey 1-Year Estimates.)
Utah has proven to be a place where individuals can increase their income potential and also improve their overall standard of living and well-being. Utah is a place where people want to work, and where companies can have a meaningful impact on the lives of their employees and on the communities where they operate. Doing business in Utah not only makes financial and logistical sense for companies – it makes financial sense for employees, too.
_____
For additional information or to schedule an interview, please contact us.
EDCUtah’s Research Minute highlights interesting economic development data and timely research insights. This month, we explore productivity by industry in Utah.
An analysis of Utah’s most productive industries reveals interesting insight into what cities, counties, and the state might consider when planning for the future and targeting expansion and development opportunities.
What qualifies as a productive industry, you ask? Productivity is the total industry output (gross domestic product, plus the value of products and services used as inputs to produce other products and services) divided by industry employment. The measure is used to estimate the dollar amount per employee, per year for an industry. The higher the dollar amount, the more productive a hypothetical employee would be in that industry.
Any increase in productivity leads to economic growth as measured by GDP, and improved economic growth diversifies industry and raises wages thus improving the standard of living. Higher productivity also often means greater impact to communities in tax revenue, higher quality jobs, and a greater multiplier effect for economic growth.
EDCUtah’s research team analyzed all 96 3-digit NAICS (North Atlantic Industry Classification System) codes in the state to determine which industries contribute most to economic growth and prosperity. To do this, EDCUtah considered metrics like productivity, employment, labor density, GDP per employee, gross surplus, and the cost of labor.
In the analysis, the most productive industries tended to be the industries with the highest GDP per employee and the highest gross surplus. This makes sense because GDP is used in the calculation for those metrics. Some of the most productive industries in Utah have high employment, and some don’t. Utah has a competitive labor density for some of these industries, but not for others. The cost of labor for the most productive industries tended to be higher than those of less productive industries, since those industries generally required higher skilled labor.
Petroleum and Coal Product Manufacturing is based on the transformation of crude petroleum and coal into usable products. The process for petroleum refining involves the separation of crude petroleum into component products using complex methods. Utah has a relatively low employment in this industry, with only about 1,800 employees statewide, but a high labor density, since this industry does not have high employment nationwide. Nevertheless, this industry has grown rapidly over the last five years (+108.9% growth) and produces an astounding $1.7 million in GDP per employee.
Contrast this industry with Food Services and Drinking Places, with 119,000 employees and only $37,000 GDP per employee, and it’s clear that some industries are far more productive than others. These two industries produce roughly similar GDP, despite one having less than 2% of the employment compared to the other.
It makes sense that some industries are not highly productive. Social assistance and residential and nursing care services do not exist to produce a product output, but to provide necessary community care. The same can be said for other institutions, like museums and historical sites, which exist to serve the public and offer cultural enrichment.
Additionally, many municipal leaders prioritize attracting retailers as part of their economic development efforts. While retail industries typically rank low in productivity, GDP per employee, and gross surplus, they can provide a significant source of local sales tax revenue. Retail and service industries also contribute to a community’s livability and workforce diversification.
Productivity data can provide community leaders with an alternative lens for assessing developable areas and evaluating their economic development plans. Some communities might choose to increase their investment in real estate and infrastructure to attract non-retail commercial businesses. Other communities may not be interested in new industry development. Prosperity and “good growth” look different for every community – that’s why EDCUtah collaborates with community leaders to understand their unique needs and help them achieve their economic development goals.
_____
For more information about how industries performed in this analysis, email us at connect@edcutah.org or explore the benefits of investing with EDCUtah.
For additional information or to schedule an interview, please contact us.
Data Sources: JobsEQ, US Bureau of Economic Analysis, US Bureau of Labor Statistics.
Each month, EDCUtah’s Research Minute highlights interesting economic development data and timely research insights. This month, we explore Utah’s economic outlook and national rankings.
The U.S. News and World Report recently ranked Utah as the best state in the nation for the second year in a row. Their “Best States” ranking uses thousands of data points across multiple categories to make their determination. Utah ranked in the top 15 states in low crime, education, healthcare, economy, fiscal stability, and infrastructure.
Utah receives recognition from other outlets as well. Utah ranked #1 for the 17th year in a row in economic outlook by Rich States Poor States. WalletHub ranked Utah as the #1 state to start a business in 2024, as well as the #2 best state economy. Why is the economy of Utah so successful, despite national and international economic and geopolitical worries?
Utah’s culture of innovation and hard work continues to be a boon for the state. According to the Kem C. Gardner Policy Institute, Utah has the highest labor force participation rate in the nation. Utah also has the ninth-lowest unemployment rate, the second-lowest poverty rate, and the second-highest median household income.
Utah’s stellar job growth was the highest in the nation for a decade, growing at a staggering rate of 32.9 percent—more than double the national average. The state’s job growth dipped over the past year, but it’s still the 11th fastest annual job growth in the nation. Utah has the youngest population in the nation by a wide margin, making it a great place for employers to find motivated and hardworking workers.
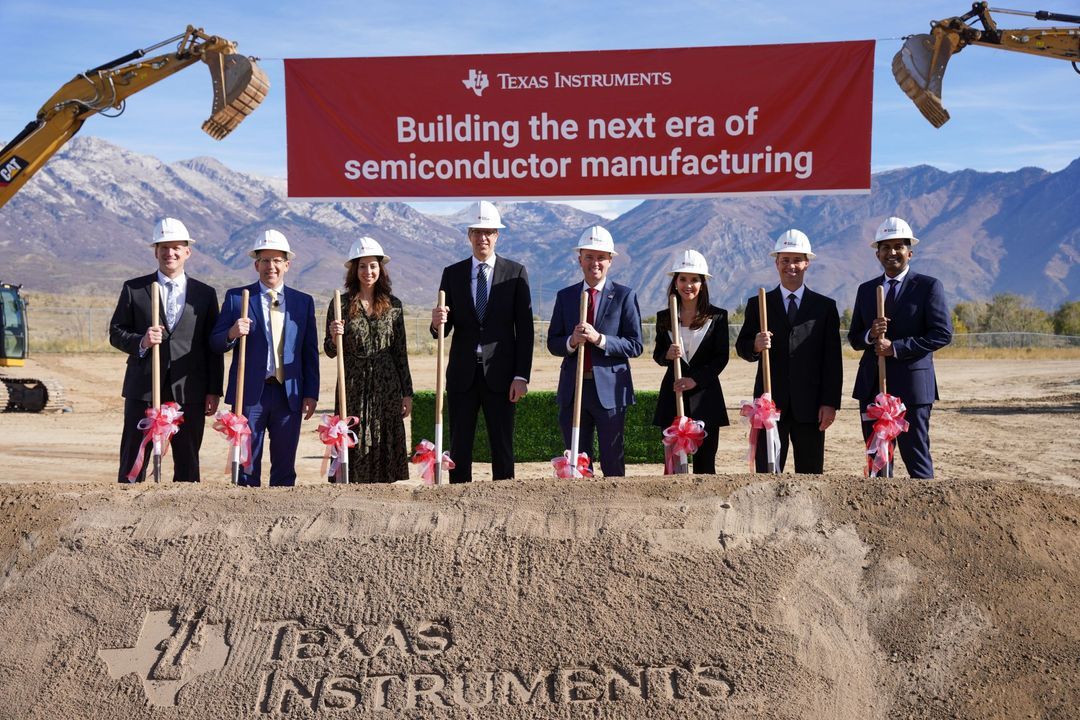
Businesses continue to see Utah’s economy as a good investment. National and international companies like Campbell Soup Company, Delta Airlines, Nature’s Bakery, Proctor & Gamble, and Texas Instruments continue to expand in Utah, bringing thousands of high-quality jobs and billions in capital investment. And Utah’s business-friendly environment, commitment to fiscal responsibility, and high quality of life continue to make Utah a great place to live, work, and play.
_____
Want more data like this? Explore the benefits of investing with EDCUtah.
For additional information or to schedule an interview, please contact us.
Data Source: JobsEQ, unless otherwise noted.
Each month, EDCUtah’s Research Minute highlights interesting economic development data and timely research insights. This month, we explore energy costs in Utah compared to the nation.
For many years, Utah has enjoyed relatively low energy costs, for both electricity and natural gas, compared to many other states in the U.S. This is true for residential, commercial, and industrial consumers. EDCUtah routinely provides energy cost data to businesses and site selectors considering Utah for expansion, and lower energy costs have been a significant driver for corporate relocation projects to Utah from high-cost states such as California and New York.
According to the U.S. Energy Information Administration, Utah has the fourth lowest electricity costs in the nation for all sectors at 9.03 cents per kilowatt hour—behind North Dakota, Wyoming, and Louisiana. In states with higher costs, residents and businesses may pay double or even triple this amount. Hawaii’s cost per kilowatt hour is 38.7, and California is at 24.73 cents per kilowatt hour. For high energy users, these costs can be more than prohibitive; they could mean the difference between success and failure as a business. In 2023, Utah also ranked fourth in the nation for cheapest natural gas costs in all sectors, behind Idaho, North Dakota, and South Dakota. However, natural gas rates have fluctuated in Utah and other states in recent months.
High inflation in the energy sector continues to be a major hurdle for residents and businesses. Energy prices rose 4.4% from January to February in 2024, registering the highest monthly increase since August 2023, according to the U.S. Bureau of Labor Statistics compiled Producer Price Index in February.
While Utah is not immune to this inflation, residents and businesses continue to enjoy relatively low energy costs in all sectors. New data shows that Utah may become the cheapest state in the nation for energy in 2024. According to an analysis of federal data, Utah is projected to have the lowest electricity rates in the nation in 2024, with the annual costs estimated to be $1,047.27 per resident. This is significantly lower than high-cost states, like Hawaii at $3,450.55, as well as the national average of $1,730.55 per resident.
Utah’s cost-effective energy can be attributed to a mixed portfolio approach to energy that includes wind, hydroelectric, and solar, according to representatives of Rocky Mountain Power. Rocky Mountain Power and Dominion Energy are the two primary electricity and natural gas providers in Utah and are committed to keeping energy affordable. Diversity and redundancy help keep Utah energy costs low. Coal and natural gas continue to be the highest producers of electricity in Utah, but renewable generation, including hydro, wind, solar, and other sources account for 359,000 MWh, increasing every year.
_____
For more information, including a breakdown of rates by category, email us at connect@edcutah.org or explore the benefits of investing with EDCUtah
For additional information or to schedule an interview, please contact us..
The EDCUtah’s Research Minute highlights interesting economic development data and timely research insights. This month, we discuss EDCUtah’s participation in a national cost of living index and how Utah measures up.
When a new corporate expansion or retention project is considering Utah for a business location, EDCUtah’s research team provides several reports to the client. One of these reports, the Operating Cost Comparison, measures the cost of doing business in Utah against other regions being considered by the company. We include wage estimates, real estate prices, utility rates, taxes, and the cost of living index.
Cost of living impacts the decisions of both individuals and companies, and site selection consultants often compare the cost of living in Utah against other states in the region. How does cost of living impact business? In some instances, a higher cost of living in a particular area may mean employers must offer higher salaries to attract and retain workers. Additionally, higher cost of living can translate to higher building costs and operating costs for the company.
Each year, researchers and regional organizations like EDCUtah collect cost of living data and submit it to the Council for Community and Economic Research (C2ER). C2ER compiles the data into a national index that measures cost of living differences among metropolitan areas. We collect price data in six categories: housing, utilities, grocery items, transportation, health care, and miscellaneous goods and services. The average of all locations that collected data that year is set to 100, and regions are then compared as a percentage above or below the average.
Policy impacts pricing! In this quarter’s collection, we noticed that the cost of name-brand insulin is down significantly. This likely reflects recent changes in legislation and the availability of insurance-covered alternatives for those with type 1 diabetes.
Because the cost of living is measured at a specific point in time and the composition of data participants changes slightly each quarter, the index cannot be used to measure price increases over time. However, it is useful to compare regional costs in relation to each other and to the nation as a whole. It’s especially helpful for comparing different regions that may be experiencing similar trends in inflation, housing costs, and more. This index is often cited in national news by outlets including Wall Street Journal, Forbes, CNNMoney, US News and World Report, and ABC News.
C2ER recently published their 2023 cost of living index, which is calculated based on the average of the previous three quarters of data. Salt Lake City received a score of 108.7, St. George 107.8, Provo 103.6, Ogden 99.9, and Cedar City 96.2.

The main reason many Utah metros measure above the national average is the price of housing—which includes both purchase price and apartment rents. The rest of the country has also seen rapid increases in housing costs, and housing costs continue to be a pain point for states including Utah, Idaho, Arizona, Washington, and Colorado.
Utah’s index scores are similar to or lower than the index scores of markets we often compete with. The index score for Miami is 116.9, Denver 110.3, Reno 104.4, Phoenix 101.9, Austin 98.9, Atlanta 98.3, and Charlotte 96.5. Utah metro areas are competitive in terms of affordability and provide a balance between costs and quality of life.

EDCUtah recently finished our first quarter data collection for four Utah metropolitan statistical areas (MSAs): Salt Lake City, Provo-Orem, Ogden-Clearfield, and the St. George metros. In the past, EDCUtah collected local data for the Salt Lake, Ogden, and Provo metros, but we recently added the St. George metro due to process developments that allow data to be collected remotely. Previously, grocery prices were collected by walking through each store—five stores per metro—and writing down prices. As grocery delivery services became more prevalent over the last few years, this data became more widely available online, which allows for web scraping.
One of the competencies that sets EDCUtah apart from other economic development organizations is our focus on quality research and economic data. Not only do we provide reports that inform decision-makers as they evaluate Utah for their next business location—we also represent Utah communities in valuable data collection projects that contribute to economic benchmarking.
_____
Want more data? Explore the benefits of investing with EDCUtah.
For additional information or to schedule an interview, please contact us.
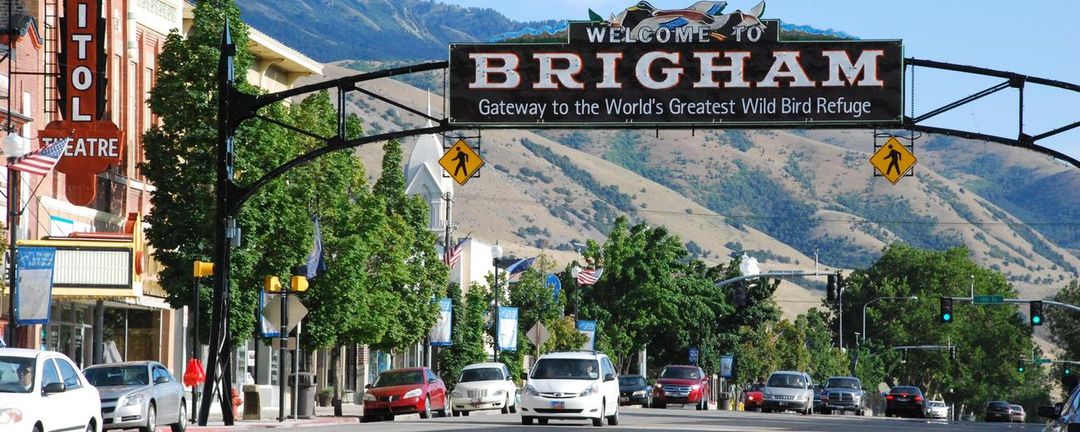
The EDCUtah’s Research Minute highlights interesting economic development data and timely research insights. This month, we explain a change in the way the federal government defines and evaluates Utah regions based on the huge population growth in Utah over the past several years.
One of the competencies that sets EDCUtah apart from other economic development organizations is our focus on quality research and economic data. EDCUtah’s research team provides data to:
Last fiscal year, EDCUtah completed 187 research requests for more than 50 projects. We also regularly update our research publications to keep a pulse on how Utah compares against regional and national competitors. For the purposes of our research, EDCUtah defines communities according to US Census Bureau defined Core Based Statistical Area (CBSA) boundaries. CBSA boundaries are used in all governmental data sources for reporting data for community regions. They provide a helpful framework for comparing locations across the nation.
The US Census Bureau recently made changes to Utah’s Core Based Statistical Areas (CBSAs) as part of their normal update rotation. The Census Bureau looks at both metropolitan statistical areas and micropolitan statistical areas and makes any necessary updates every five years. Utah’s areas have not been changed in more than a decade, but changes were made in 2023 based on population center guidelines that the US Census Bureau uses to determine the areas.
These changes impact how data is collected and reported by the federal government and how Utah is perceived by site selectors and companies considering Utah for expansion opportunities.
The Salt Lake City, UT MSA is now called the Salt Lake City-Murray, UT MSA. The boundaries of the MSA remain the same and include both Salt Lake County and Tooele County. The Provo-Orem, UT MSA is now called the Provo-Orem-Lehi, UT MSA. The boundary for this MSA remains the same as well, encompassing Utah County and Juab County. The Logan, UT-ID MSA, comprised of Cache County and Franklin County, ID has not changed, nor has the St. George, UT MSA, which includes just Washington County.
In northern Utah, the US Census Bureau changed the boundaries of one metropolitan statistical area and created a new micro area. The Ogden-Clearfield, UT MSA was renamed the Ogden, UT MSA and now includes Davis County, Weber County, and Morgan County. Box Elder County was removed from the former MSA and assigned to a new micropolitan area called the Brigham City, UT-ID micro area. This new micro area also includes Oneida County, ID.
Rich County has also been added to the Evanston, WY micro area, which was renamed the Evanston, WY-UT micro area. Utah’s other four micropolitan statistical areas remain the same.
These changes reflect the significant growth that Utah has experienced over the past decade, both on the Wasatch Front and off, particularly for Brigham City and other population centers in Box Elder County. Utah’s population growth over the last decade is the highest in the nation at 18.4%. This is more than double the national average of 7.4%. While the old 2020 map is still available online, the US Census Bureau has not yet released new maps that reflect the recent changes. It will take time for these updates to be made on government and private websites and to be reflected in data and available resources. EDCUtah will make necessary adjustments to our data and marketing materials as this new information becomes available.
_____
Want more data? Explore the benefits of investing with EDCUtah.
For additional information or to schedule an interview, please contact us.